How to Reduce Late Payments Small Business UK: 2026 Expert Guide
10 October 2026
Chasing overdue invoices can feel like a never-ending battle for UK small business owners. Late payments disrupt cash flow, threaten your ability to pay suppliers and staff, and cause unnecessary stress. If you’re wondering how to reduce late payments small business UK, you’re not alone—and there are proven strategies that really work.
Key Takeaways
- How to reduce late payments small business UK involves combining clear terms, smart invoicing, and proactive credit control.
- Embracing technology can significantly minimise late payments small business UK.
- Knowing UK late payment legislation empowers you to act quickly and legally.
- Open client communication and regular reviews support cash flow stability.
- Best practices for timely client payments boost your business’s reputation and resilience.
The Impact of Late Payments on Small Firms in the United Kingdom
Financial Consequences and Lost Opportunities
Late payments are more than a minor inconvenience—they can be a major threat to the survival and growth of UK SMEs. The 2026 Federation of Small Businesses survey revealed that 54% of small firms reported late or unpaid invoices in the past year, with an average delay of 23 days beyond agreed terms. This leads to cash flow gaps, missed supplier payments, and even the risk of insolvency. The impact of late payments on small firms UK-wide is estimated to cost the economy over £20 billion annually.
Operational Disruptions and Stress
When cash flow is unpredictable, business owners may delay growth plans, struggle to pay employees, or have to negotiate with creditors. Staff morale can be affected, and relationships with suppliers may suffer, especially if your business becomes known for slow payments. Preventing late payment issues for SMEs is essential for maintaining trust and stability in the United Kingdom’s competitive marketplace.
How to Reduce Late Payments Small Business UK: Best Practices
Setting and Communicating Payment Terms
The first step in how to reduce late payments small business UK is to establish clear, written payment terms before any work begins. Specify due dates, accepted payment methods, and late payment penalties in every contract and invoice. Clearly communicate these terms to clients and confirm their understanding. Many UK businesses use 14 or 30-day payment periods; always follow up with written confirmation for new clients. This simple action is among the most effective strategies to avoid late payments UK business owners can deploy.
Professional and Timely Invoicing
Effective invoicing techniques for UK businesses are critical. Make sure your invoices are clear, accurate, and sent promptly. Include your business name, contact information, purchase details, payment due date, and bank details. Using cloud-based accounting software streamlines this process, reduces mistakes, and enables quicker resolution if there are disputes. Want to know how to improve cash flow in small business? Start by getting invoices out within 24 hours of completing work or delivery.
Encouraging Prompt Payment from Clients
Polite reminders, both before and after the due date, can significantly reduce payment delays in the UK. Consider offering an early payment discount (e.g., 2% off if paid within 7 days) or charging statutory interest on overdue amounts. Personal follow-up messages often prompt clients who simply forgot. Consistently applying these best practices for timely client payments can reinforce your professionalism and encourage prompt settlement.
Leverage Technology and Automation to Minimise Late Payments
Automated Reminders and Digital Tools
Adopting technology is a powerful way to minimise late payments small business UK. Automated invoice reminders via email or SMS nudge clients when payment is due or overdue, reducing the need for awkward conversations. Most leading UK accounting platforms—such as Xero, QuickBooks, and Sage—offer built-in reminder features and allow tracking of unpaid invoices. These tools also generate reports to help you identify chronic late payers and take pre-emptive action.
Flexible Payment Platforms
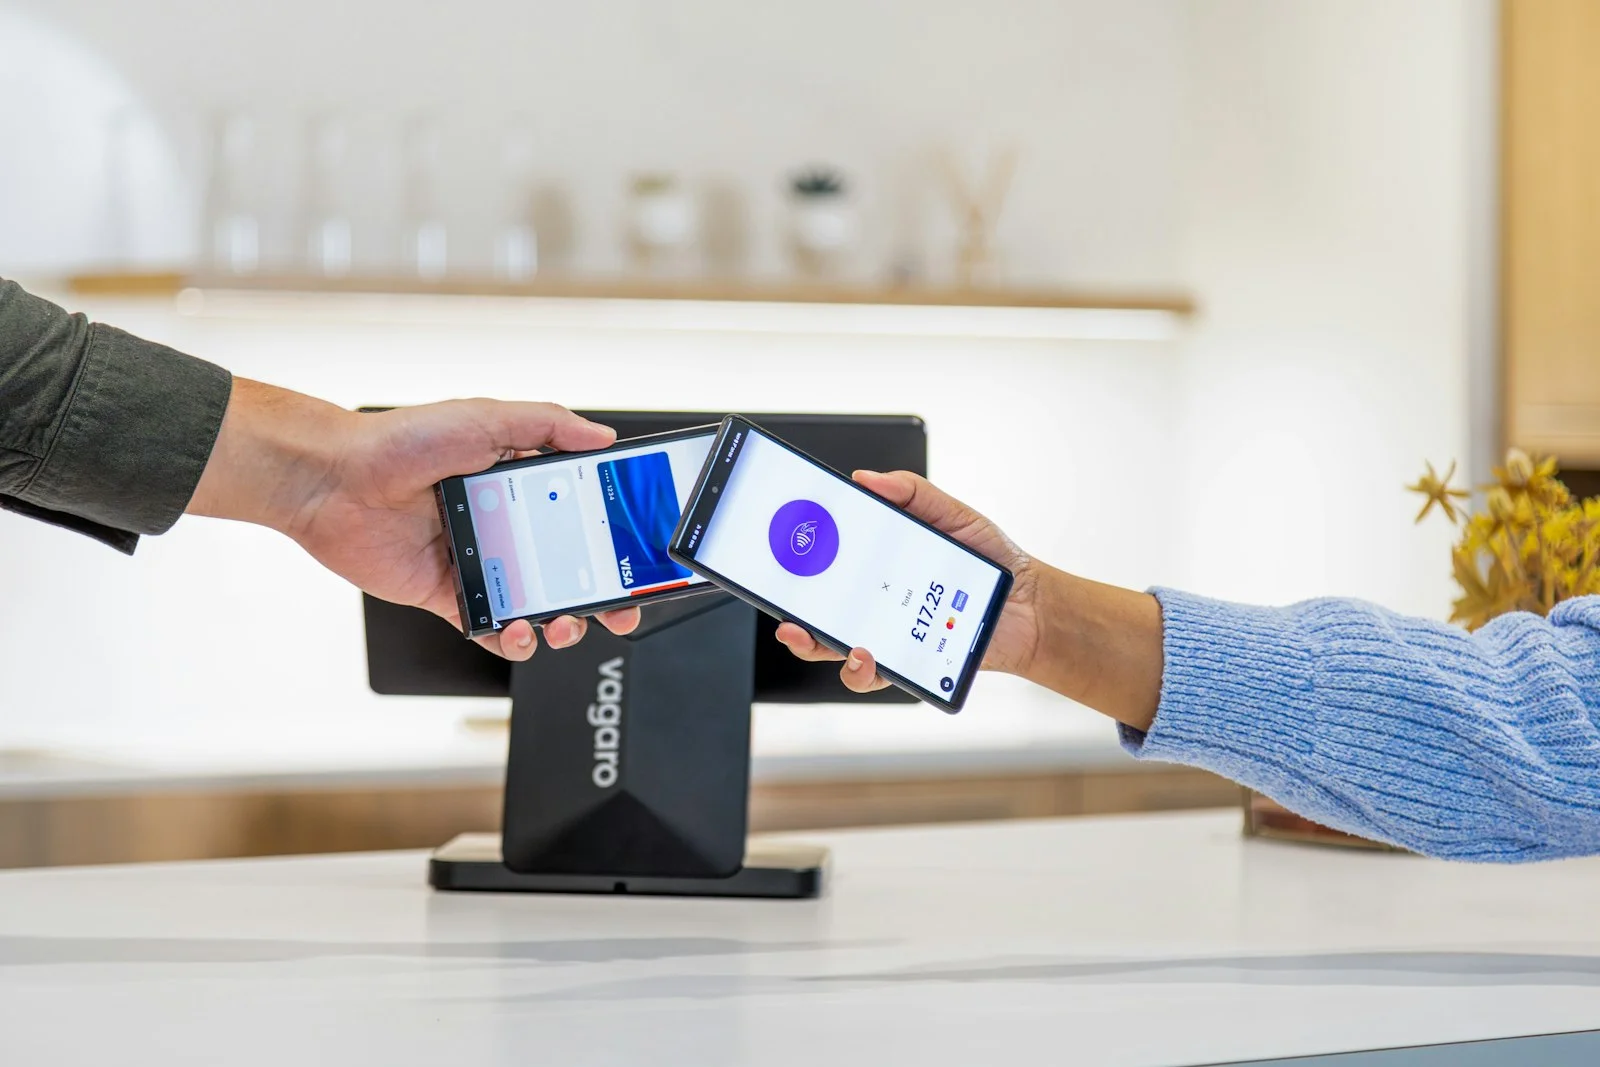
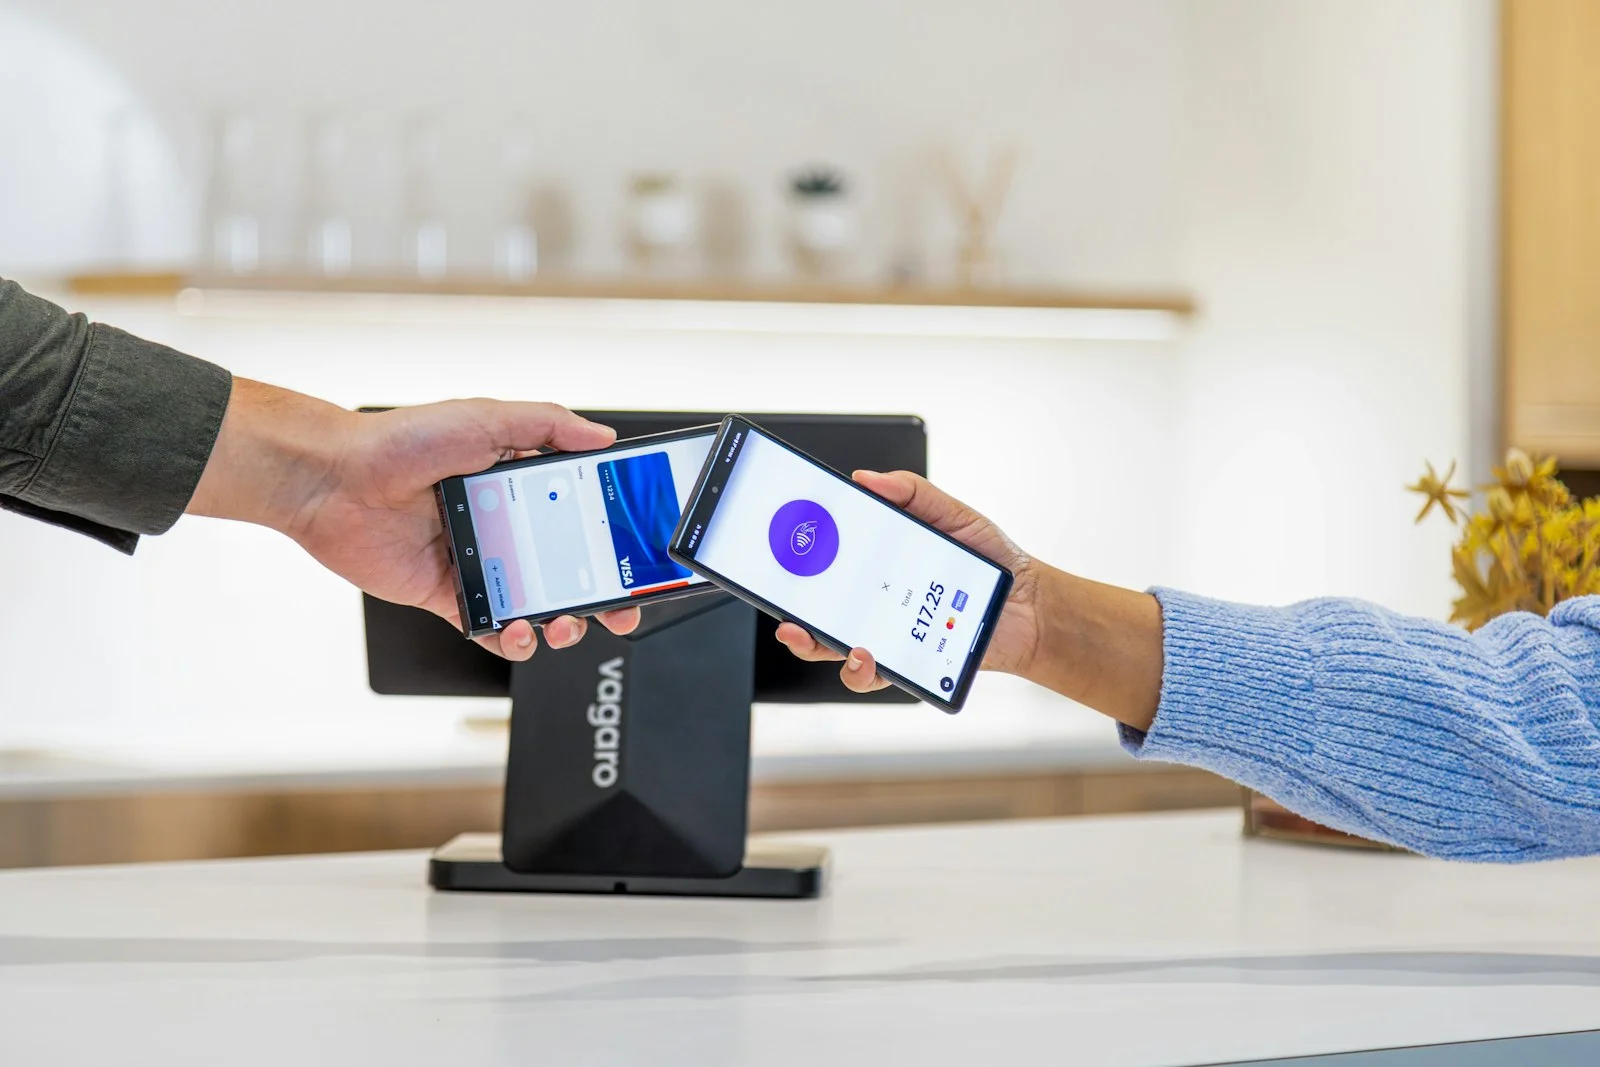
Offering customers multiple, convenient payment methods can help reduce overdue invoices UK-wide. Accepting bank transfers, debit/credit cards, or Direct Debit increases the likelihood of on-time payment. The table below compares popular UK payment platforms and their key features for small businesses.
| Platform | Payment Methods | Typical Fees | Ideal Use Case |
|---|---|---|---|
| GoCardless | Direct Debit | 1% + 20p per transaction | Recurring/subscription payments |
| Stripe | Cards, Apple Pay, Google Pay | 1.4% + 20p (UK cards) | Online sales, instant checkout |
| PayPal | Cards, PayPal wallet | 2.9% + 30p per transaction | International clients |
| BACS | Bank transfer | Low (via bank) | Large, one-off UK invoices |
Integrating Invoicing and Payment Systems
Linking your invoicing platform with payment gateways accelerates settlement and reduces manual admin. Many UK SMEs now send invoices with a ‘Pay Now’ button, allowing clients to pay instantly by card or bank transfer. This ease of use is a proven solution for late payment problems in the UK, particularly for service-based businesses.
Credit Control: Preventing Late Payment Issues for SMEs
Assessing Credit Risk
Preventing late payment issues for SMEs starts with effective credit control. Run credit checks on new clients using reputable UK agencies such as Experian or Creditsafe. Set lower credit limits or request partial upfront payment from high-risk customers. Maintaining a record of clients’ payment histories helps you spot patterns and act early if habits change.
Client Relationship Management
Building good relationships with clients can often resolve issues before they arise. Keep communication open, confirm receipt of invoices, and don’t be afraid to discuss payment expectations. If a client consistently pays late, consider revising terms or requiring advance payment. Regular reviews and open dialogue are among the best strategies to avoid late payments UK SMEs can implement.
Legal Options and UK Late Payment Legislation for Businesses
Statutory Rights and Compensation
UK law provides robust support for small businesses facing overdue invoices. The Late Payment of Commercial Debts (Interest) Act entitles you to charge 8% above the Bank of England base rate on late payments, as well as fixed compensation. These rights apply automatically unless your contract specifies otherwise. Familiarise yourself with these provisions at gov.uk to ensure you’re protected.
Steps to Take When Payments Are Late
If payment is overdue, begin with a firm but polite reminder, then escalate to a formal demand letter referencing your right to charge interest. If this fails, consider mediation, a statutory demand, or—if the debt is below £10,000—using the UK small claims court. The process is designed to be accessible for SMEs and can be the most effective solution for late payment problems in the UK. Always keep a detailed record of all communications and agreements.
When to Use Debt Collection or Legal Services
For persistent or large debts, you may need to engage a debt collection agency or seek legal advice. Ensure any agency complies with UK regulations and is transparent about fees. While this can strain client relationships, it sends a clear message that your business takes payment seriously. Understand your rights and obligations by consulting the Financial Conduct Authority (FCA).
Practical Tips for Reducing Overdue Invoices UK
Regular Credit Control Reviews
Schedule monthly reviews of your accounts receivable to spot overdue invoices early. Segment clients by payment history and prioritise follow-up with chronic late payers. This proactive approach is vital for those wondering how to reduce late payments small business UK, as it prevents small issues from escalating.
Staff Training and Delegation
Train your team on effective credit control processes and customer communication. Delegating responsibility for chasing payments ensures accountability. Even the smallest UK business benefits from consistent procedures and clear roles regarding payment collection.
Professionalism in Every Interaction
Maintaining a polite, firm, and professional tone builds trust and respect. Thank clients for prompt payment, and handle disputes swiftly and fairly. This not only improves your cash flow but also enhances your business reputation across the United Kingdom.
Frequently Asked Questions
What are the first steps to reduce late payments in my UK small business?
Start by setting out clear payment terms, invoicing promptly, and communicating openly with clients. Use automated reminders and regularly review your receivables to catch late payments early.
How can small businesses manage cash flow when faced with late payments?
Monitor cash flow weekly, keep a cash buffer, and negotiate flexible terms with your suppliers if needed. Strong credit control and early client vetting also help manage risk and support healthy finances.
Are there penalties for clients who pay late in the UK?
Yes. Under UK late payment legislation for businesses, you can charge 8% above the Bank of England base rate and claim compensation on commercial debts. Always state this right in your contracts and invoices.
What effective invoicing techniques help reduce overdue invoices UK?
Use detailed, professional invoices with payment terms clearly highlighted. Send invoices immediately upon completion of work, and follow up with reminders ahead of the due date to encourage prompt payment from clients.
What should I do if a client repeatedly pays late?
Consider revising their payment terms, requesting deposits, or even refusing further credit. If necessary, escalate to legal action or a debt collection agency, ensuring you follow UK regulations and maintain thorough records.
Tackling late payments is a reality for every business owner in the United Kingdom, but it doesn’t have to be a constant worry. By applying these practical strategies for how to reduce late payments small business UK, you can protect your cash flow, strengthen client relationships, and give your business the stability it deserves. For more impartial guidance and up-to-date insights on managing your SME finances, explore Fin-Tech UK’s expert resources and independent advice.